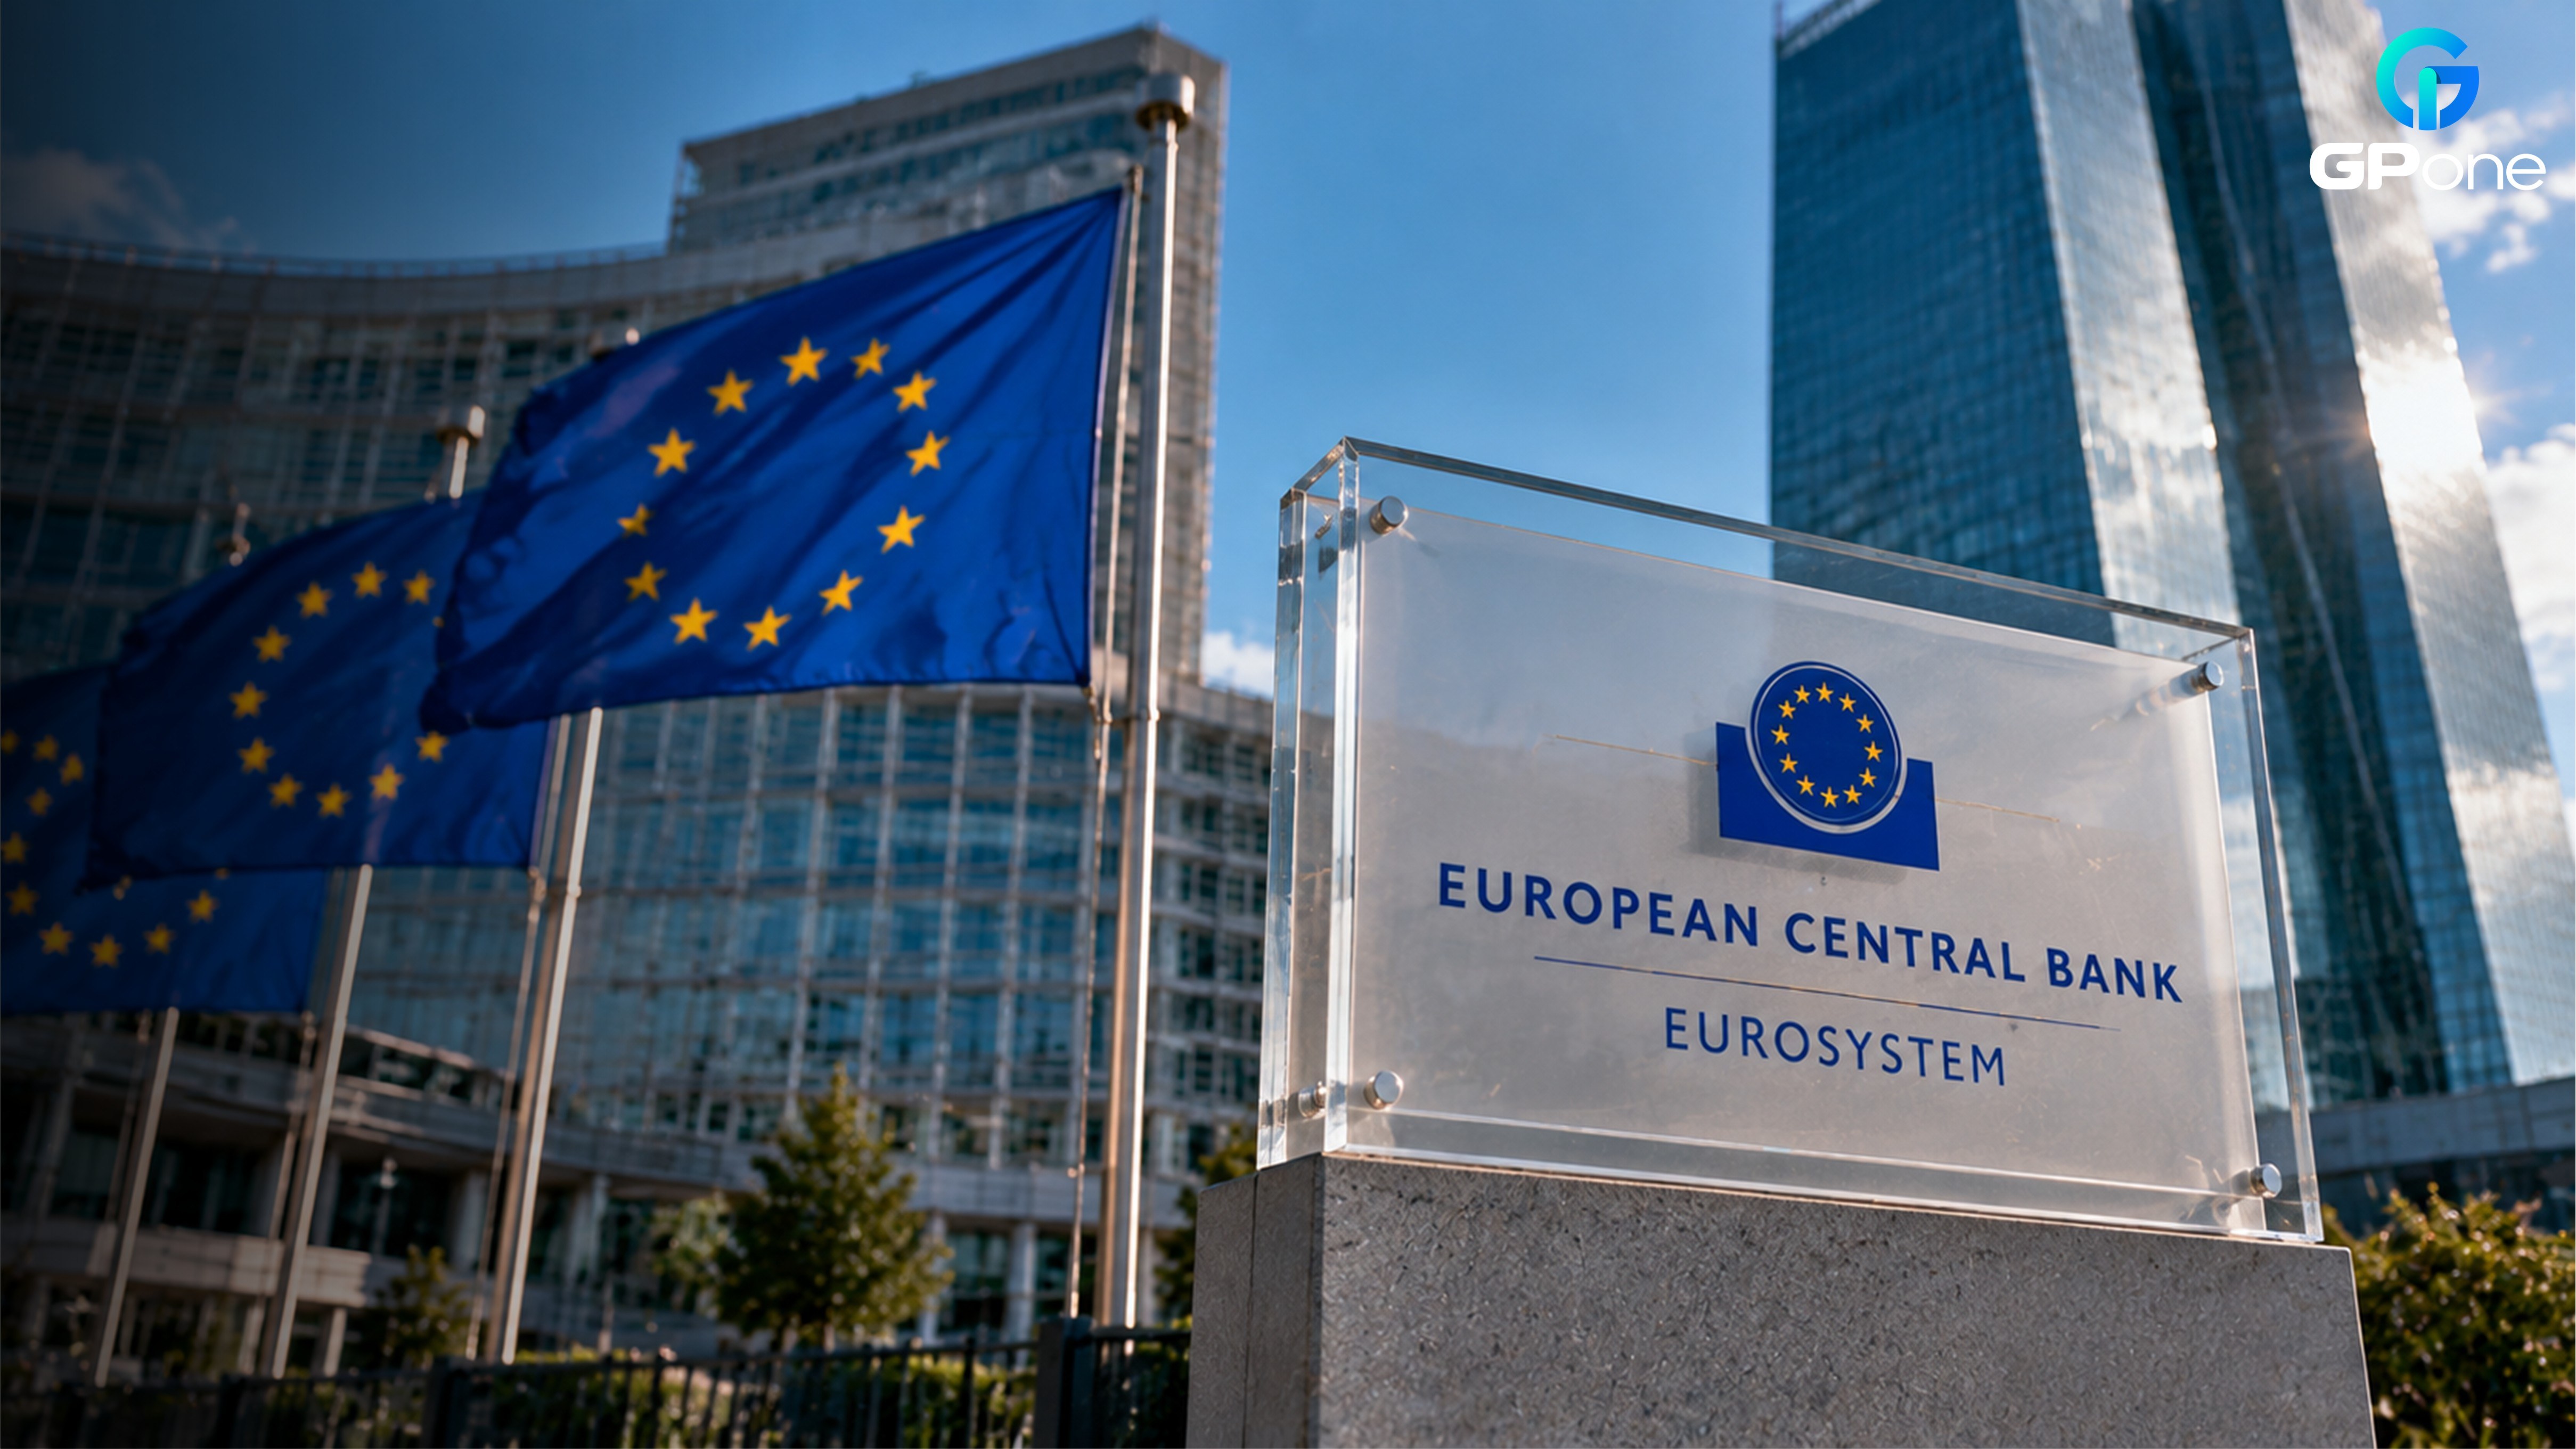
On 21 September 2026, the European Central Bank (ECB) announced the Eurosystem’s launch of Pontes, enabling wholesale transactions in tokenized assets to settle in central bank money. The service connects market distributed ledger technology (DLT) platforms with the Eurosystem’s existing TARGET Services. An initial group of banks, market infrastructures and DLT operators has completed onboarding, with further participants set to join gradually. Additional features and longer operating hours will be introduced in stages, with full implementation expected by 2028.
Executing a trade is not the same as settling it
Once a buyer and seller agree on a price, the securities still need to be delivered against payment. Settlement risk arises if the asset is delivered but the agreed funds do not arrive, or if payment is completed without delivery of the asset.
Tokenization can improve recordkeeping and coordination between processes. It does not, by itself, ensure that the asset used for payment is sufficiently reliable or can be transferred on time.
Central bank money for the cash leg
Pontes enables the cash leg of tokenized wholesale transactions to settle in central bank money, providing a more reliable settlement foundation for transactions between institutions. It is separate from the digital euro project intended for everyday retail payments and does not mean that the ECB has endorsed all tokenized assets on the market.
The ECB’s announcement makes clear that the initial service offering is limited, with further capabilities to be added in response to market needs and technological developments.
From putting assets on-chain to completing delivery and payment
For the digital asset industry, this development moves the discussion from whether assets can be recorded on-chain to whether assets and funds can be exchanged securely. Even a market with a trading interface and quoted prices still needs to address funding sources, clearing arrangements, settlement timing and the handling of exceptions.
If platforms do not connect effectively, the liquidity visible to users may remain fragmented across separate systems rather than form a single pool of executable market depth.
What this means for individual users
In the near term, Pontes is primarily an infrastructure initiative for institutional markets. Its launch does not directly change the stablecoin balance in an individual’s wallet or the rate of return offered by a platform.
The broader lesson is practical: when assessing a digital asset service, consider asset records, price formation, cash settlement and exit mechanisms together. Claims of improved liquidity become meaningfully testable only when both trade execution and settlement are clearly explained.